
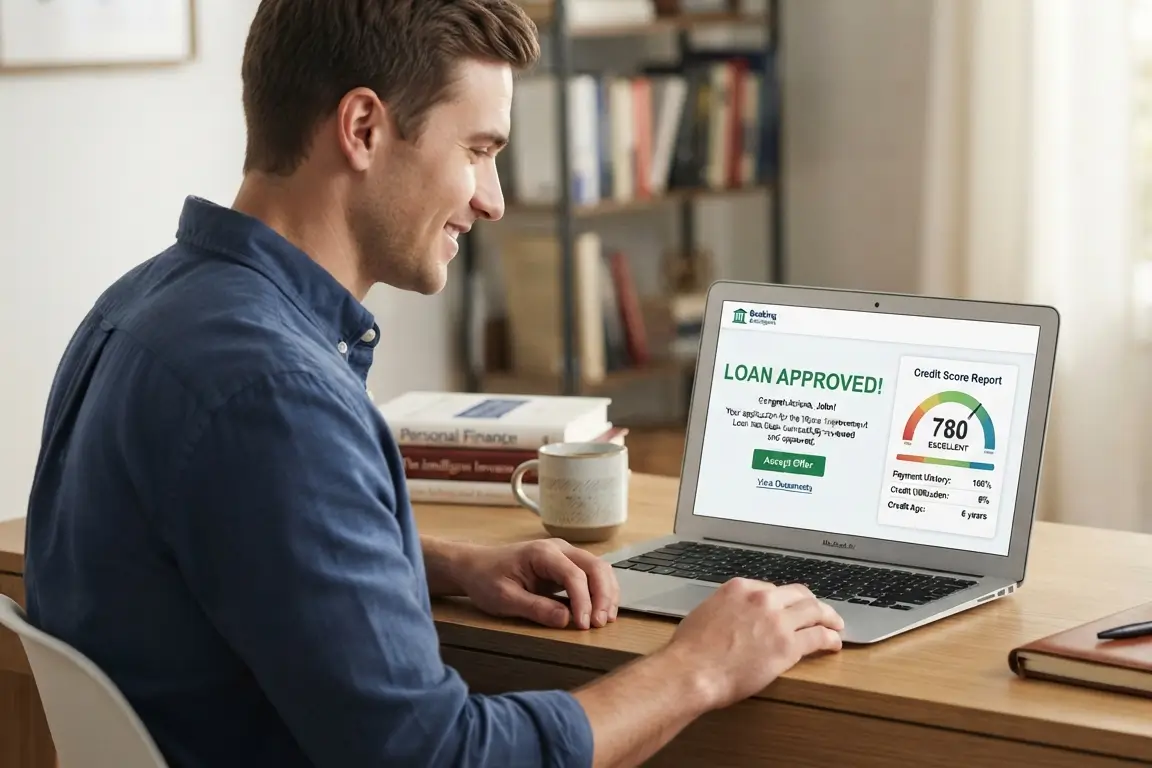
Yes, you can get an online personal loan with a bad credit score, but it may take more work and cost more than a loan for someone with strong credit. Online lenders look at more than just your credit score. They may also consider your income, employment, existing debts, payment history, and other information when reviewing your application.
If your credit score is low, you should not assume that every lender will reject you. At the same time, you should avoid applying to every lender you find online. Too many applications can make your situation harder to manage.
What Is Considered Bad Credit?
Credit scoring systems can vary. In the U.S., FICO scores generally range from 300 to 850. A lower score can make it harder to qualify for loans and may lead to less favorable loan terms. Many lenders consider scores below 580 to be poor credit, although each lender can use its own requirements. Your credit score does not tell the entire story. For example, someone with a low score but steady income may have more borrowing options than someone with a similar score and unstable income. That is why you should look at your complete financial situation before applying for a personal loan.
Can You Get a Personal Loan With Bad Credit Online?
Yes. Some online lenders work with borrowers who have less-than-perfect credit. However, approval is never guaranteed. Lenders usually review your ability to repay the personal loan before making a decision.
A lender may look at:
- Credit score and credit history
- Monthly income
- Employment or income stability
- Existing debts
- Debt-to-income ratio
- Requested loan amount
- Payment history
Some lenders may accept applicants with lower credit scores, while others may have minimum credit requirements.
Why Online Lenders May Be an Option
Online lenders can make the application process convenient. You can often complete an application from home and receive a decision without visiting a bank branch. Some lenders also allow you to check whether you may qualify before completing a full application. When available, this can help you compare potential options without immediately committing to a loan. Still, convenience does not mean the personal loan will be cheap. Always look at the total cost before accepting an offer.
How Do Bad Credit Personal Loans Work?
A bad credit personal loan generally works like other personal loans. You borrow a fixed amount and agree to repay it over a specific period. Your monthly payment usually includes part of the amount you borrowed plus interest and any applicable fees.
For example, suppose you borrow $5,000 for an emergency expense. The lender may give you a repayment period of several years. Your monthly payment will depend on the interest rate, loan term, fees, and other terms.
A longer repayment period can reduce your monthly payment but may increase the total amount you pay over the life of the loan. That is why you should consider both the monthly payment and the total repayment amount.
What Can You Expect With Bad Credit?
Having bad credit can affect the terms a lender offers you. You may face a higher interest rate than a borrower with stronger credit. You may also receive a smaller loan amount or a shorter repayment period.
Some lenders may ask for additional information about your income and financial situation. The important point is to compare the complete loan offer rather than focusing only on whether you were approved.
Look at the APR
The annual percentage rate, or APR, helps you understand the cost of borrowing because it can include the interest rate and certain fees.
For example, two lenders may offer the same personal loan amount but have different APRs. The personal loan with the lower APR may cost less overall, assuming other terms are similar.
Read the personal loan agreement carefully before accepting anything.
What If You Cannot Get Approved?
A personal loan rejection does not mean you have no options. First, check why the lender rejected your application if the lender provides a reason. Your credit report may contain errors that affect your score. You can review your credit reports and dispute inaccurate information with the appropriate credit reporting agency.
You can also consider whether you really need to borrow the full amount. If you need $2,000 but can cover $500 from savings, borrowing less may reduce your future monthly payments and overall interest cost. Another option may involve waiting and improving your credit before applying again if the expense is not urgent.
How to Improve Your Chances of Getting a Personal Loan
There is no guaranteed way to get approved, but you can improve your financial profile before applying.
1. Check Your Credit Reports
Review your credit reports for inaccurate accounts, incorrect balances, or other errors. Correcting genuine errors can help make sure lenders see accurate information. Do not pay a company simply because it promises to remove accurate negative information from your credit history. Be cautious about credit repair services that make unrealistic promises.
2. Show Stable Income
Lenders want to know that you can repay the money. A steady source of income can help demonstrate your ability to make monthly payments. Be prepared to provide information about your income if the lender requests it.
3. Reduce Existing Debt
Existing debt can affect how lenders view your ability to take on another monthly payment. If possible, paying down credit card balances or other debts before applying may improve your overall financial position.
4. Borrow Only What You Need
A larger loan is not necessarily a better loan. Borrowing more means you generally have more money to repay. If you only need enough money to cover a specific expense, avoid increasing the loan simply because the lender offers a higher amount.
Watch Out for Bad Credit Loan Scams
People with bad credit can become easy targets for loan scams because they may feel desperate for approval. Be especially careful if someone promises guaranteed approval regardless of your credit history.
You should also be cautious if a company demands an unusual upfront payment before providing a loan. Never send money or personal information simply because someone says you have been “pre-approved.”
Check the lender’s identity and terms before sharing sensitive financial information.
Common Warning Signs
Be cautious when a lender:
- Guarantees approval without checking your financial information
- Pressures you to act immediately
- Requests unusual upfront payments
- Does not clearly explain loan costs
- Asks for sensitive information through an unverified website
- Makes promises that sound too good to be true
Take your time and verify who you are dealing with.
Are Online Personal Loans Safe?
Online personal loans can be legitimate, but you should research the lender before applying. Check the lender’s website, loan terms, privacy information, fees, and contact details. You should also make sure you understand how the lender handles your personal and financial information.
Do not assume that a professional-looking website automatically means the company is trustworthy. Before accepting a loan, make sure you know the interest rate, APR, fees, monthly payment, repayment period, and total amount you may have to repay.
Alternatives to a Bad Credit Personal Loan
A personal loan may not always be the right solution. If you need money for an emergency, consider whether you have savings available or whether you can negotiate a payment arrangement with the company you owe. Depending on your situation, you might also consider a credit union or another legitimate financial institution that offers small-dollar borrowing options.
For medical bills or other large expenses, ask the provider whether it offers a payment plan before taking on a high-cost loan. The best option depends on why you need the money and how much you can realistically afford to repay each month.
Final Thoughts
You can get an online personal loan with a bad credit score, but approval and loan terms depend on the lender and your overall financial situation. Do not choose a loan simply because you qualify. Compare the APR, fees, monthly payment, repayment period, and total repayment amount.
If the loan would make it difficult to pay your rent, utilities, food, or other essential bills, stop and reconsider the borrowing amount. A bad credit score does not permanently prevent you from getting credit. But borrowing carefully and making payments on time can help you avoid making an already difficult financial situation worse.
